GEE GROUP WRITE UP 11/14/2024
Gee Group (JOB) currently presents a compelling opportunity at $0.26/share with industry sentiment at its lowest and a beaten stock price to levels where it does not justify current forward valuation. It is also worth noting it is trading slightly below tangible book value and sitting on a stash of cash with 70% of its market cap in cash.
Company Overview
Gee Group is a temporary staffing (87.3%) and direct placement (12.3%) agency based in the US. GEE operates in three segments: Industrial staffing, Professional staffing, and Direct Placement. The company targets multiple verticals including IT, Accounting and Finance, Medical Scribes, Light Industrial (blue collar), and Engineering. The company has become relevant in the past 10 years as they started growing through acquisitions when Derek Dewan, the CEO, took charge in 2015. At that time, GEE and Scribe (where Dewan was the CEO) merged and became GEE Group. Ever since then, the company has grown through acquisitions in the fragmented industry of temporary staffing. As reference, in 2015 the company had $43m in revenues and in 2023 it was at $152m.
Snapshot:
Price: $0.26
Market Cap: $28m
EV: $8.4m
Shares Outstanding: 110m
Why does the opportunity exist?
Besides being a very small company with zero analyst coverage, the industry is not very hot right now. The staffing industry is highly cyclical and tied with economic activity.
Gee Group has been losing money during the downturn and recently got hit with a big goodwill impairment charge of $20m, the stock is down 55% from a year ago. Investors also seem to not like their new capital allocation strategy which is to fuel growth via organic growth and acquisitions.
With the past 2 years with horrible performance and very ugly industry dynamics, this might be a pass for anyone that looks at it on a surface level. However, if we take a closer look, we find out the high operating leverage of the business and capital light nature that allows for high FCF generation. With significant cost improvements and emphasis on operating efficiency, GEE Group is poised for strong outperformance when the cycle turns.
On a high level, the labor market recently started to loosen up, coming from high inflation down to tamed inflation with high interest rates which led businesses across the US and all over the world to lay off a ton of workers and employ hiring freezes. This led the unemployment rate to rise to around 4.1%.
Temp staff is the first one to get hit when the economy slows down. Due to the nature and flexibility of temp staffing, they are the ones that get fired first during a downturn, and the first ones to get hired when activity increases. This is a key reason why companies use staffing agencies. The staffing agency bears the risk of employing the person and they just charge a markup on their wage to the client company. So the client company bears no employment risk, has no responsibility, and can fire the worker whenever they want.
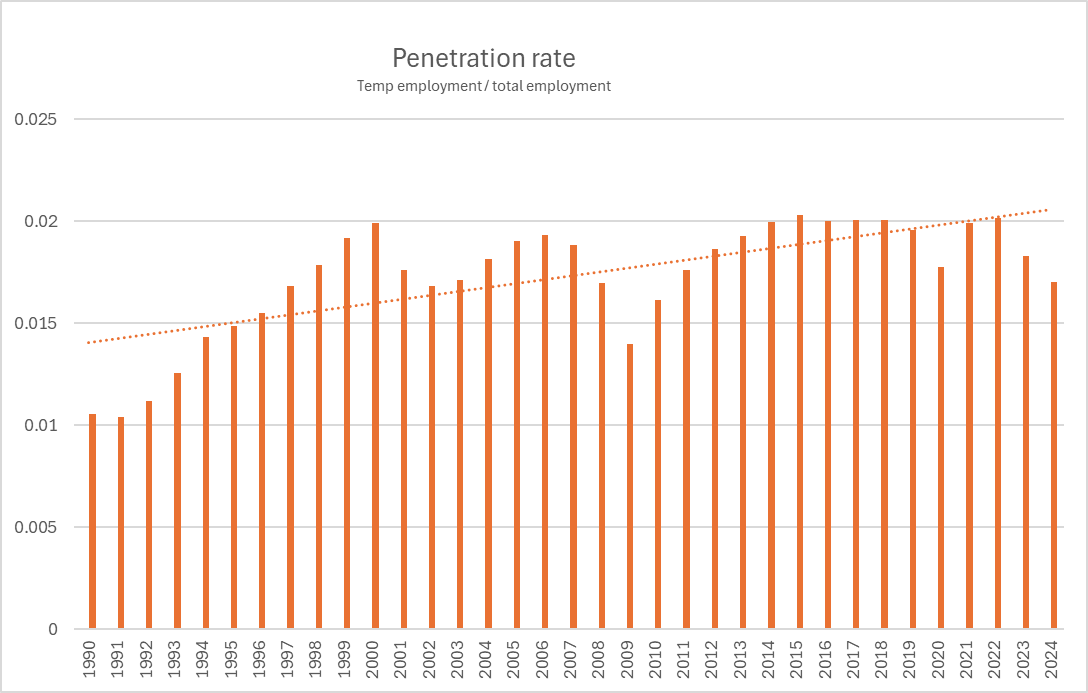
The temp staff penetration rate (temporary workers/employment) has averaged around 1.9% in normal environments and 2% in very good environments. Currently the penetration rate is sitting at 1.68%, significantly below trend.
Catalysts
Penetration rate reverses to the mean
The penetration rate has been going on an upward trend as companies use temp staffing more and more due to the flexibility it provides and the desire of a more variable cost structure. I think this is highly likely as this is basically believing in the US economy which is the world’s powerhouse. From 1.68% to 1.9% is an increase of 13% and there are high correlations between penetration rate growth and the industry’s revenue growth.
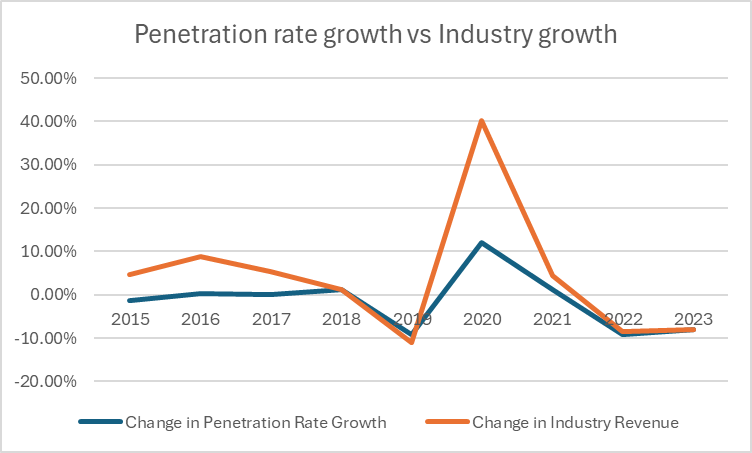
Unfortunately, I did not have access to a longer time frame, but I think this frames the picture pretty well. Usually, industry grows above the growth in penetration rate, so we can see a bigger increase than 13% in industry growth when penetration rate reaches 1.9% again.
Accretive Acquisitions
This is a controversial take as investors only want buybacks and dividends, but I do believe they will benefit greatly today with acquisitions due to the market environment. They will be able to get more attractive valuations at cheaper multiples and it could be very accretive to earnings. Here is CEOs reply to a question in their latest earnings call (Q3 2024) regarding what they define as an accretive acquisition:
“Yes. Accretive acquisitions, in our mind, are acquisitions that would be profitable from the get go or at the most a very, very short time after the acquisition, and would add to our earnings per share, and to our EBITDA.”
In a fragmented industry like the staffing industry, acquisitions are necessary to fuel growth. There are over 25,000 staffing agencies in the US, most of them are small regional local firms. Gee Group is trying to become more of a national firm by scaling through integration of acquisitions. I think this is the best capital allocation policy currently.
Also worth noting that they could become an acquisition target. The CEOs past company, MPS group, was sold to Adecco for $1B+ back in 2009.
Management also mentioned that they have received offers to be acquired:
“And the answer is we get inquiries from time-to-time, most recently two days ago, as to a potential, a merger or strategic acquisition, going the other way to enhance someone else’s growth strategy and make us a part of it. All of those will be looked at and brought to the directors to review in conjunction with senior management, when and if those opportunities become meaningful.
But at this point, we believe we’re undervalued in any type of transaction like that may not be beneficial in the longer run, but of course that’s a decision that is not unilaterally made by anybody company.”
Reinstatement of buybacks
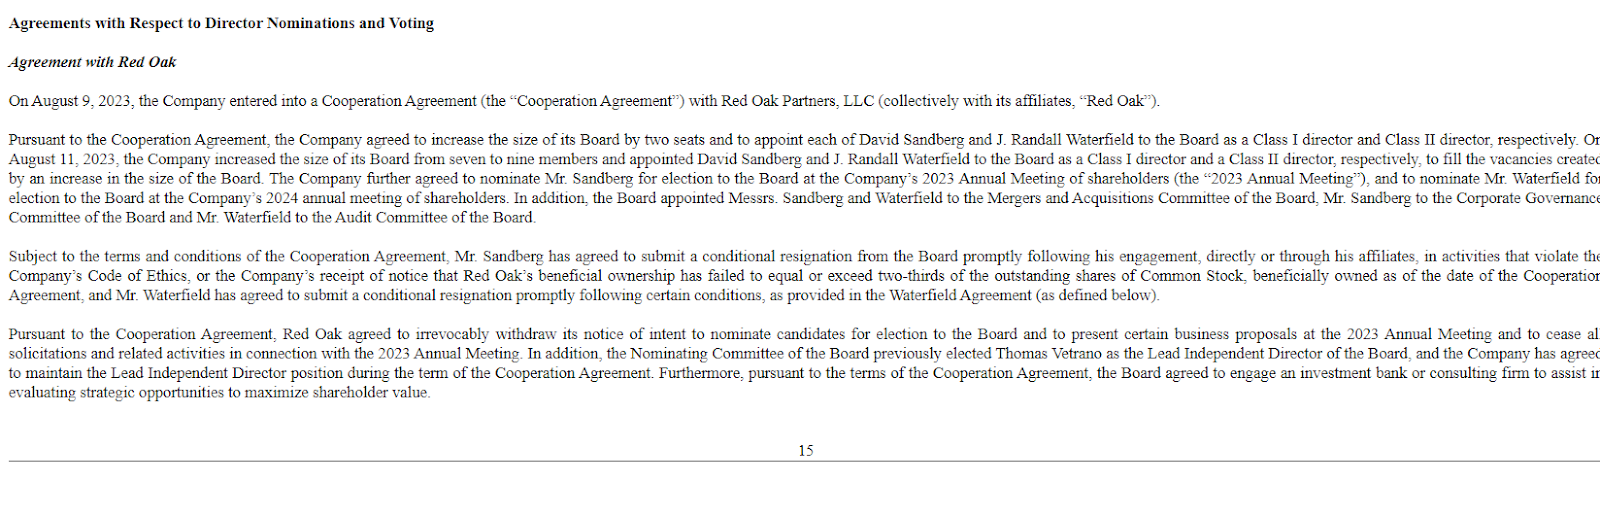
About a year ago the company incorporated a buyback program due to increased pressure from activist fund Red Oak Partners. The company made an agreement with Red Oak Partners that will improve corporate governance with the PM of Red Oak sitting in the BOD and one of his nominations as well. However, the buyback expired in December 2023 and was replaced with the acquisition capital allocation, receiving criticism from shareholders.
Valuation
I believe the company is currently trading at 1.8x my normal EBIT estimates. That is sheer undervaluation. I believe they will be able to come back stronger due to the intensity of the fall of the penetration rate and based on comments from CEOs in the industry, there are a lot of projects that were deferred due to the state of the economy and the uncertainty. These projects will have to be done sooner or later and especially in the IT segment, they will benefit greatly from this pent-up demand. Pre covid EBIT hovered at around $3.15m, I believe they can do $4.7m EBIT in a normal environment. At its peak when labor markets were booming, their EBIT went as high as $9m.
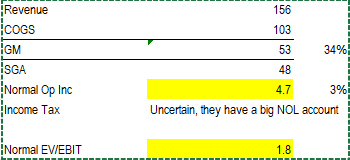
At a normal 10x EBIT multiple gives us an upside of 134%.
The margin of safety is relatively high as the company’s current TBV/share is $0.22 vs the current share price of $0.26.
*This valuation is not inclusive of the potential accretion to earnings from future acquisitions, which are expected to happen in FY25. I also caught myself being too conservative in my revenue estimates as they likely will grow at a higher rate than the industry given acquisitions and organic growth.
Risks
Overpaying for acquisition
Self-explanatory, any bad acquisition whether it’s overpaying or using too much debt can reduce the value of the company. In the past they have run into problems with over leveraging. They did that with SNI which almost took the company bankrupt. However, they were able to raise capital and pay everything off and start off from a clean slate at the expense of shareholders. However, it was necessary but would have been preventable. Goob392 at VIC outlines this situation very well.
Timing
The timing of the cycle could take longer than expected. There is a possibility that things can get worse from here.


do you think that this is still a buy?
LikeLike
I’m still long but still a lot of pain ahead
LikeLike